Editor's Note: If you're a current Golden Portfolio paid member and missed Tuesday's update regarding one of our top recommendations' Q2 financial results, Click here (membership sign-in required). This company reported record numbers across nearly all metrics. If you are not yet a paid Golden Portfolio member but would like access, please join here.
I talk a lot about gold prices and gold miners in this free publication. That’s because gold prices are fun to talk about in a bull market, and gold stocks are exciting when they’re hitting paydirt.
It’s enticing to look at the news this week, for instance, and see that the Federal Reserve is again, starting to embrace yield curve manipulation – a sign that they’re losing control of interest rates. This kind of uncertainty typically benefits gold. Investors will own low interest bonds… or high interest bonds – but they prefer gold if they don’t know what’s coming next.
I think we’re still relatively early in the gold bull market and that’s especially true when you look at the actions of President Trump and the Treasury Secretary Bessent – who are both rabidly trying to cheapen the dollar…
It’s an exciting time to be a gold investor.
Every week, out of the dozens of gold miners I cover, we get a handful of them reporting drill results, showing the potential path to riches if you own these companies while they develop their mines into production. And many of these companies do go on to become wildly successful, turning their potential into cashflow as they start to produce gold. It’s why my service dedicated to gold miners (Golden Portfolio 10X) is up an average of 74%…
But there’s another type of gold company that’s actually my favorite to own. These companies rarely have much news. They’re not hitting paydirt. They’re not releasing flashy public relations blurbs to the media about a new monster gold find on their property.
I’m talking about royalty firms. These companies take tiny royalty stakes in the production from gold miners in exchange for up front capital.
There’s no other business like these royalty firms. I believe they’re not just the best gold companies to own for the long term, but probably the best stocks in general.
They’re such a unique business model that there’s no other publicly traded company you can compare them to.
But imagine if you could go back to 1960 to buy a 1% stake in the total annual sales of The Beatles. Maybe it would have cost you $50k or something. A big chunk of change for you – but it would have allowed Paul to buy a fancy fretless jazz bass, or George a nice new professional acoustic guitar. New suits for all 4 of them, maybe a down payment on a tour bus…
But within a decade or so, your up front cash would have generated hundreds of thousands for you, and by now, potentially hundreds of millions.
That’s exactly what these royalty businesses do – but instead of buying the rights to music, they buy the rights to production from a gold mine.
That’s it. They don’t own any equipment, they don’t drill holes. They barely have any employees. Most have tiny corporate offices that could fit inside of a tennis court.
The whole point of these royalty firms is to find promising, up and coming gold mines, and provide capital so the gold mine owners can develop their mines. Then they sit back and wait for the mine to become productive. Sometimes it takes a decade or more.
But you’d happily wait for a decade to get production from a world class mine – just like you would wait for the Beatles catalog to mature to the point that it’s generating massive amounts of cash.
The lack of “paydirt” moments for these royalty firms means that most gold investors yawn when they hear about them. They’re looking for the quick, exciting “eureka.”
But as a 20 year gold analyst, I can confidently tell you that gold royalty firms are what you want to own for the long term. Just like you’d want to own the Beatles catalog for decades, not months or years.
These companies have massive leverage to increases in the price of gold because they have almost no overhead. Every dollar increase in the price of gold hits their bottom line. It’s why these companies outperform not just gold and other gold stocks, but nearly any other stock you can care to name over the long term.
And it’s why my Golden Portfolio (GP) service (dedicated entirely to gold royalty firms) has slightly outperformed even my best gold miner stocks, with an average gain of 80% in 2025 alone.
I currently cover 16 royalty firms in my GP service. All of them are still under my target price. That’s because these firms are still being valued by the market as if gold was at $1,500 or $2,500 – instead of at $3,400 or more.
If that sounds strange, I agree, but you have to realize that it takes a while for higher gold prices to truly manifest both in the financials of gold miners, but more importantly, in the minds of investors.
Many gold investors have a long memory – and recall painfully the 12+ destruction that occurred in gold stocks after 2012.
$3,400 gold just doesn’t register, because they’re still wincing from $1,200 gold.
And we’re still a long way from the average investor paying much attention to gold stocks. According to the World Gold Council, only about 1% of global investment capital is invested in gold.
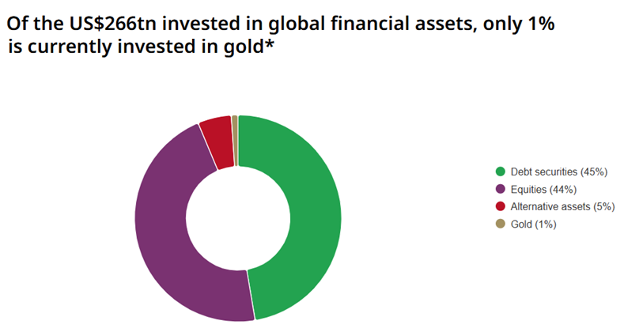
That means it would only take another 1% investment to double the whole market. If the percentage reached the ~4% long term average of global investment capital, it quadruples…
And while I expect my gold miners to surge with any influx of capital into the gold market, I know the long term performance is going to be in royalties.
Definitely check out my Golden Portfolio (GP) service if you’re looking for long term success from gold.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio