I hate to say, “I told you so.”
But I’ve been talking about Newmont Corp (NYSE: NEM) as a bellwether for the whole gold mining sector for months now.
Back in February I wrote to my Golden Opportunity readers:
“Newmont is trading at a 48% discount to fair value based on FCF.
It’s the cheapest it’s been in over a decade.
The stock is trading with a 20% FCF yield.
That means you have the opportunity to buy $1 of FCF profits for $0.20 cents.
This is the same metric I used to identify Newmarket Gold and SilverCrest Metals – both of which became multiple 1,000%+ winners for my readers.”
Since I mentioned Newmont in February, the stock is up almost 50%:
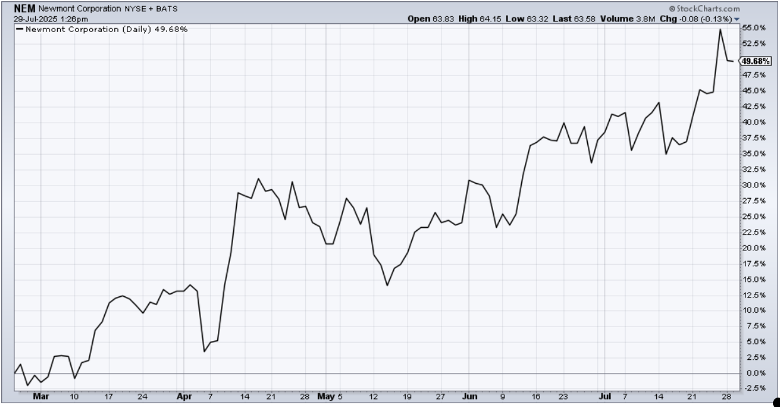
It’s up 75% year to date. That last bump came after Newmont posted one of their strongest quarters ever, producing $1.7 billion in cash flow, and over 1.5 million ounces of gold in Q2 alone.
The company also announced plans to buy back $3 billion worth of stock, and it will maintain its $0.25/share dividend, which will return a total of $1 billion to shareholders in 2025.
But it’s not just Newmont that I’ve been talking about. In my paid research, I told my readers that a company called Orogen had the best assets. I told them Sandstorm was trading at the biggest discount. I told them that Silvercrest and MAG Silver were the best and most profitable silver miners.
In the past 2 months, all of these companies have been taken over at substantial premiums to what I recommended them at.
I knew Newmont was a screaming deal. I predicted that Warren Buffett would take a stake in the company, because it’s one of the only large cap companies trading at such an attractive valuation. I still think Buffett might wade into shares of Newmont or another undervalued gold major… though he hasn’t yet.
I don’t tend to recommend gold majors in my paid services for a few reasons. For one, I think there’s better upside in smaller companies. My main investment thesis for gold miners is that you generally want to own them before they’re taking large amounts of gold out of the ground. Every ounce depleted from a gold mine means the mine is worth that much less in the market. Companies like Newmont are on a perpetual treadmill of needing to replenish their gold reserves. One way they can replenish is to buy gold juniors…
Another reason I don’t recommend gold majors in my paid services is I don’t think it’s providing much value to paid subscribers to tell them about big, obvious gold majors they hear about from every mainstream outlet. Newmont (along with Barrick, Agnico Eagle, etc.) are in every “top 5 gold stocks to buy now” list.
The good news is that despite a significant run-up in both the general gold market and my paid services, almost all of the companies I cover are still selling for a massive discount to their net asset value.
I mentioned that Newmont was selling at a 48% discount… but the vast majority of the companies in my paid portfolios are still selling for even bigger discounts…
The market is very slowly starting to wake up to large caps like Newmont being undervalued. They haven’t yet sniffed out the juniors.
We’re still early in this trend.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio